The Federal Reserve faces a difficult combination of risks: the investment boom surrounding artificial intelligence is supporting economic growth and markets, while also intensifying inflationary pressures and resource shortages. Market participants are divided over whether high interest rates can cool the boom. Fed Chair Kevin Warsh believes borrowing costs affect AI investment, while those taking a more radical view argue that the technology’s enormous potential returns could weaken the usual effect of interest rates. For the regulator, the challenge is not just how to prevent overheating, but also how to avoid stifling one of the economy’s main sources of growth.
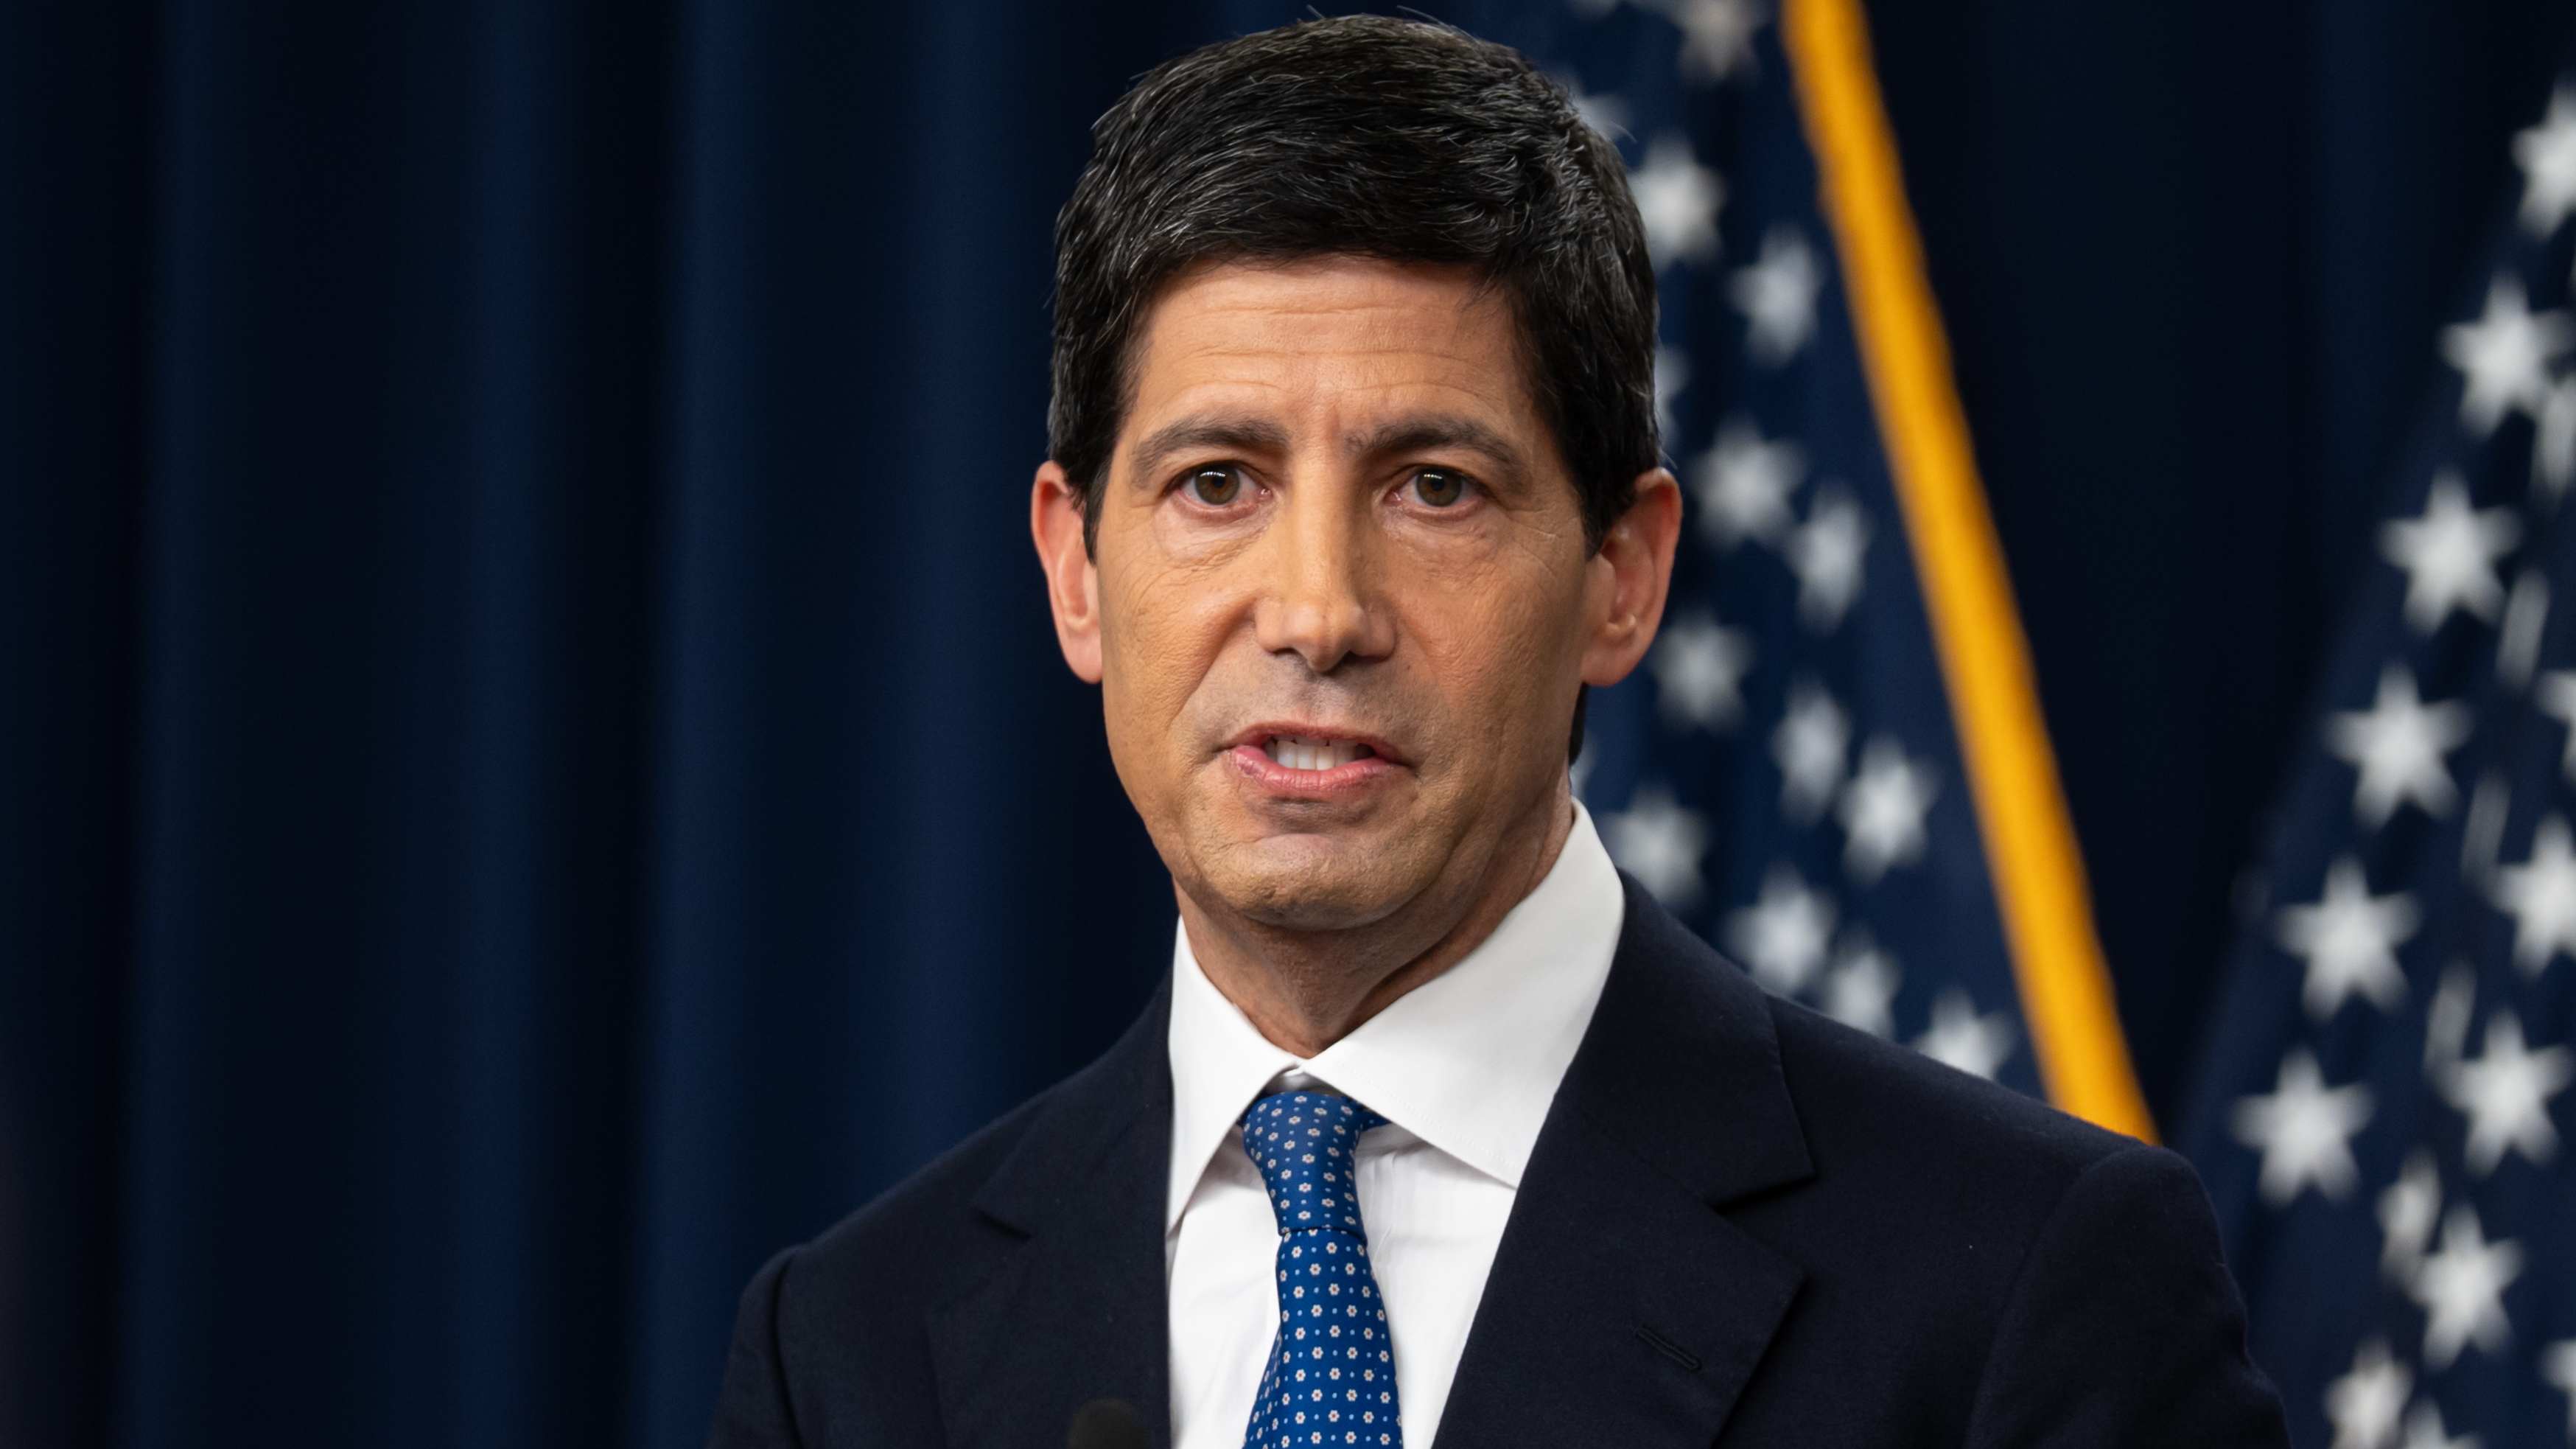
According to Yahoo Finance, the Fed left interest rates unchanged, though the decision was made in a split vote. At a press conference, Warsh rejected the suggestion that higher rates would have little effect on demand for artificial intelligence. “Interest rates permeate all areas. They affect almost everything, directly or indirectly,” he said. New technologies, he added, do not exist apart from the rest of the economy: the cost of capital, the availability of credit, and changing financial-market conditions can all affect technology companies.
Warsh took issue with a position previously expressed by Pershing Square chief Bill Ackman. Ackman argued that demand for computing capacity and investment in AI could prove resilient to high interest rates because “winning the race for superintelligence” promises virtually unlimited returns. If the potential profits are that large, traditional models linking expensive borrowing to lower investment may work less well. Warsh, however, pointed to tighter financial conditions and widening credit spreads on some assets following the rate increase in September. In his assessment, the market is already distinguishing between technology companies and other businesses, meaning investors do not view the entire sector as immune to the cost of money.
A broader economic paradox is described by Politico. Building data centers requires substantial investment, electricity, equipment, construction work, and skilled workers. Rapidly growing demand for these resources can create shortages and push up prices. At the same time, rising stock prices generate wealth for investors and support consumer spending, while technology companies and their suppliers are pouring significant sums into new projects. In this way, AI is both fueling economic activity and making the fight against inflation more difficult.
The Fed faces two undesirable scenarios. If it raises rates too sharply, it could slow investment in AI infrastructure and weaken a significant source of growth. But if it acts cautiously and too slowly, inflationary pressure driven by strong demand and limited supply could become entrenched. As Claudia Sahm, a former Fed employee and now chief economist at New Century Advisors, notes, a moderate cooling in demand for AI infrastructure could give production time to catch up and ease bottlenecks.
That does not mean that a decline in AI investment would automatically solve the inflation problem. The effect depends on which spending slows, how quickly the supply of electricity and equipment expands, and whether demand from other industries holds up. In addition, a pullback in investment could hurt contractors, chipmakers, and data-center operators, as well as markets where rising technology stocks support consumer spending. The regulator’s concern, therefore, is not simply the pace of the investment boom, but how demand compares with the economy’s ability to meet it without a sharp rise in prices.
Market reactions show that investors do not view the technology sector as a single bloc. A brief update from Investor’s Business Daily reported that, after the market had risen for three straight days, Microsoft shares later gained on strong results, while Alphabet, ServiceNow, and Fortinet shares fell noticeably following their earnings reports. This snapshot does not directly link the share-price moves to the Fed’s decision: company-specific results also affected prices. But it illustrates an important backdrop: investors are increasingly assessing technology businesses by their individual prospects and financial performance, rather than simply by the broader enthusiasm around AI.
The central debate is about how monetary policy is transmitted through the new economy. An interest rate is the cost of borrowing; when it rises, project financing typically becomes more expensive and investments whose returns are expected in the future become less attractive. But the anticipated returns for AI companies may be so high that they continue investing even when borrowing is costly. That does not eliminate the impact of interest rates, but it may change its strength and distribution: the most promising companies will retain access to capital, while riskier projects will face constraints sooner.
A credit spread—the difference in yield between debt instruments with different levels of risk—is one indicator of investors’ willingness to finance companies and projects. A widening spread usually means lenders are demanding greater compensation for risk. That is why Warsh’s remarks about spreads matter not as proof that an AI downturn is inevitable, but as a sign that financial conditions can affect the sector through capital markets, even if demand for computing remains high.
Overall, these reports show that the AI boom is becoming not just a technological issue for the Fed, but a macroeconomic one. It is changing investment, consumption, and demand for energy and construction resources all at once, making it harder to gauge how much interest rates will cool the economy. If production capacity and energy supplies expand quickly enough, current shortages may ease without sharply curbing demand. If infrastructure constraints persist, the regulator will have to balance the risk of sustained inflation against the harm that could be done to a growing sector. Warsh’s main point is that even a potentially revolutionary technology is not beyond the reach of economic and financial conditions—but the scale and speed of their effects remain uncertain.